
Imagine you are going to buy a house. How do you start the planning process? Do you only look at the houses your friends own? Do you look at the neighborhoods they live in and only use the mortgage companies they use? By nature, we are drawn to comparison, and comparing apples to apples can give you a baseline to know if you are on track with your retirement plan. But how do you make sense of the contradictory and overwhelming information available in light of your own unique situation?
Comparing the Numbers
With Baby Boomers retiring every day, the Census Bureau predicts that the population aged 65 and over will grow 50% between 2015 and 2030. Because of this, the US Government Accountability Office was tasked with finding out how well prepared American workers are for retirement. They published a comprehensive report in 2015 (1) that we can use to see if your retirement savings are on par with others your age.
Whether you think you’re on top of things or way behind, you may be surprised by what statistics show about retirement savings. Let these numbers serve you as a pat on the back or a kick in the pants.
If You’re Between the Ages of 55 and 64
It may surprise you, but if you have at least $1 saved for retirement, you’re doing better than 41% of those surveyed, and if you have at least $25,000 saved, you’re in the top 59%. Though those numbers may make you feel good about yourself, they don’t guarantee you a comfortable retirement. While you may not know how much you need for retirement, we can be sure it’s more than $25,000.
Here is a table from the GAO’s report showing how resources are divided between households with and without retirement savings in this age group.
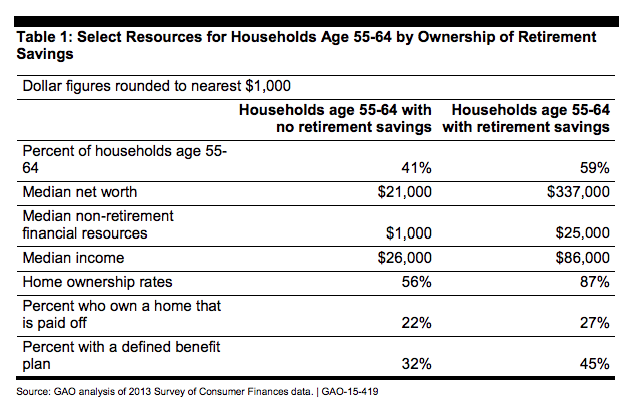
Clearly, those without retirement savings don’t have a lot to fall back on. Since they lack additional resources, they will be dependent upon pension plans and Social Security to carry them through their retirement years. Of the 59% that have saved, the median nest egg is only about $104,000. With increasing longevity and health care costs, that probably won’t be enough for a worry-free retirement.
In Table 2, you can see how much savers have actually managed to put away. Where do you fit in?
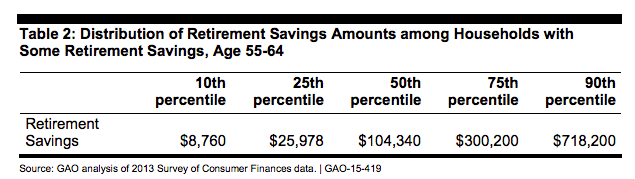
In this age group, it seems that only the very top savers are ready for retirement. Most of them are still working, though. What about those a decade older? How do you compare to those who have already reached retirement?
If You’re Between the Ages of 65 and 74
65 is a popular retirement age, though more and more people are extending this date so they can catch up with their retirement savings. Like the previous age group, this bracket doesn’t have much in savings. Here is a chart showing the exact same information as the previous age bracket.
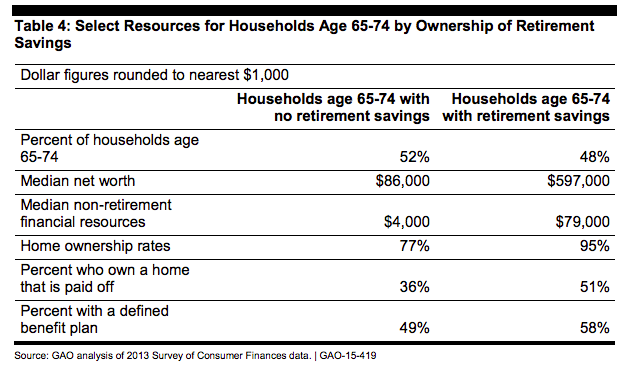
In this age group, people are a little more prepared but with only a slightly larger nest egg. However, the median net worth has increased and homeownership rates are higher. Let’s look at their savings breakdown.
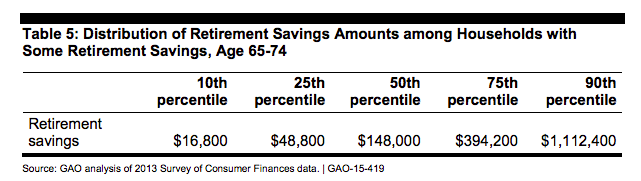
Surprisingly, the median amount saved is not significantly higher than that among households aged 55-64. It only increases from $104,000 to $148,000. The lower percentiles nearly double their savings. Where do you fall? If you’re in the 90th percentile, you are probably okay assuming modest spending. But what about the lower percentiles?
It doesn’t take a whole lot of savings to look good relative to your peers. But how are your savings relative to your current lifestyle? Will you have enough to live the life you want or do you need to double down and save more?
Your Personal Retirement Goals
No matter how you compare to your peers, you need to figure out how your savings compare to the cost of the retirement you desire. There are plenty of online retirement calculators available, but they are often generic and don’t take into account the various factors that will impact your personal situation.
The only way to have a clear idea of what you’ll need to retire comfortably is to have a financial advisor run a thorough analysis. A professional can utilize technology to show you different possible retirement outcomes and how to prepare for both the good and the bad.
How I Can Help
You may think that if you don’t have much saved you don’t have enough to work with an advisor. The truth is, you can’t afford not to work with an advisor. You need to build wealth and partnering with an experienced professional is the best way to do that.
At Newbridge Wealth Management, our goal is to provide you with a solid financial plan that will lessen your stress. We want to help you pursue a life with fewer worries, more clarity, and greater financial flexibility. Don’t keep yourself up at night wondering if you will have enough money to retire. Schedule a free 15-minute introductory phone call now!
About Vincent
Vincent R. Barbera, CFP®, MSFS is a managing partner and co-founder of Newbridge Wealth Management, a private financial counseling firm located in Berwyn, Pennsylvania. Believing in a patient, disciplined approach to investment management that delivers value and peace of mind, he utilizes a process-driven approach to financial planning that provides comfort and clarity to his client’s long-term goals. Along with a bachelor’s in psychology and business, he has a master’s in business and financial planning and Certified Financial Planner™ designation. Learn more by connecting with Vincent on LinkedIn or send him questions at vincent@newbridgewealth.com.
______


